Published on 8 November 2026 by Ramy Hanna
Primary keyword: grant acquittal checklist
\n
Grant Acquittal Checklist: 10 Things to Prepare Before the Due Date
A grant acquittal is your organisation's report to a funder showing how the grant was spent and what it achieved. Most acquittal problems are not caused by the report itself. They come from records that were never set up properly when the grant arrived.
This checklist is a practical companion to our longer [guide to grant acquittals for Australian NFPs](/insights/grant-acquittal-nfp-australia). Work through it at the start of every grant, then again a month before the acquittal is due.
Quick Summary
- Read the grant agreement first. It sets the rules, not general practice.
- Track each grant separately in your accounts from day one.
- Keep evidence for every payment, matched to the approved budget.
- Deal with unspent funds and budget changes before the due date, not after.
- Get the right sign-off, and check whether an audit or review is required.
The 10-point checklist
1. Find the acquittal requirements in the agreement
Locate the clauses on reporting, acquittal, audit and repayment. Note the due date, the reporting template, and who must sign. Different funders have very different rules, so never assume one grant works like another.
2. Put the due date in your compliance calendar
Add the acquittal date, any milestone reports, and a reminder six weeks earlier. Give each date a named owner.
3. Set up separate tracking in your accounts
Create a tracking category, project or account code for the grant so all income and expenses can be reported on their own. Doing this at the start is far easier than reconstructing it later.
4. Match the budget to your account codes
The funder approved a budget with specific line items. Map each line to your account codes so actual spending can be compared to budget line by line.
5. Keep evidence for every transaction
Store invoices, receipts, payroll records and bank statements for each grant expense. Some funders ask for samples, others for everything. Label files so they can be found quickly.
6. Allocate shared costs on a reasonable basis
If staff or overheads are shared across programs, document how you allocate them, such as time sheets or a fixed percentage. Check the agreement allows these costs before you charge them.
7. Check for variations and approvals
If you moved money between budget lines or changed the project, confirm you had written approval if the agreement requires it. Unapproved changes are a common reason for funders to query an acquittal.
8. Work out any unspent funds early
Calculate the unspent balance well before the due date. The agreement may require you to return it, ask permission to carry it forward, or apply it to approved purposes. Raise it with the funder early.
9. Prepare the outcomes report
Most funders want to know what the grant achieved, not just how it was spent. Collect participant numbers, outputs and outcomes against the measures in the agreement as you go.
10. Arrange sign-off, and audit or review if required
Confirm who must certify the acquittal, such as the CEO, treasurer or board. Check whether the funder requires an independent audit or review, and book your auditor early if so.
A simple acquittal timeline
| When | What to do | | --- | --- | | Grant received | Steps 1 to 4: agreement, calendar, tracking, budget map | | Every month | Steps 5 and 6: evidence and shared cost allocation | | Any change | Step 7: written approval for variations | | 6 weeks before due | Steps 8 and 9: unspent funds and outcomes | | 2 to 4 weeks before due | Step 10: review, sign-off and audit if required |
Governance and record keeping
Grant compliance is a board responsibility. Under ACNC Governance Standard 5, Responsible People must oversee the charity's finances responsibly. A late or inaccurate acquittal can mean repaying funds and damaging your relationship with a funder, so the board should know which grants are due and whether they are on track.
The ACNC requires registered charities to keep financial and operational records for seven years. Some grant agreements require you to keep records for longer, so check each agreement and follow whichever period is longer. For every grant, keep:
- the signed grant agreement, variations and funder correspondence
- the approved budget and the mapping to your account codes
- invoices, receipts and payroll records for every grant expense
- the method and evidence for shared cost allocations
- the lodged acquittal, outcomes report and sign-off
- board or committee minutes approving the acquittal
A simple grants register, listing each grant, its due dates, its owner and its status, gives the board a one-page view of grant risk.
Frequently Asked Questions
Q: What is a grant acquittal? A: It is the report you give a funder at the end of a grant, showing how the money was spent against the approved budget and what the grant achieved.
Q: Do all grants need an audited acquittal? A: No. Requirements depend on the funder and the grant agreement. Some accept a certified financial statement, while others require an independent audit or review.
Q: What happens to unspent grant money? A: It depends on the agreement. You may need to repay it, or ask the funder for permission to carry it forward or use it for another approved purpose.
The Bottom Line
Good acquittals start on the day the grant arrives. Separate tracking, a budget mapped to your accounts and monthly evidence collection turn the acquittal into a short reporting task instead of a scramble.
Official guidance
- [ACNC: Governance Standards](https://www.acnc.gov.au/tools/factsheets/small-charities-library-acnc-governance-standards)
- [ACNC: Record keeping](https://www.acnc.gov.au/tools/topic-guides/record-keeping)
This article is general information only. Always follow the terms of your grant agreement.
Book a Free 30-Minute Board Briefing to talk about your grant reporting. Book now →\n
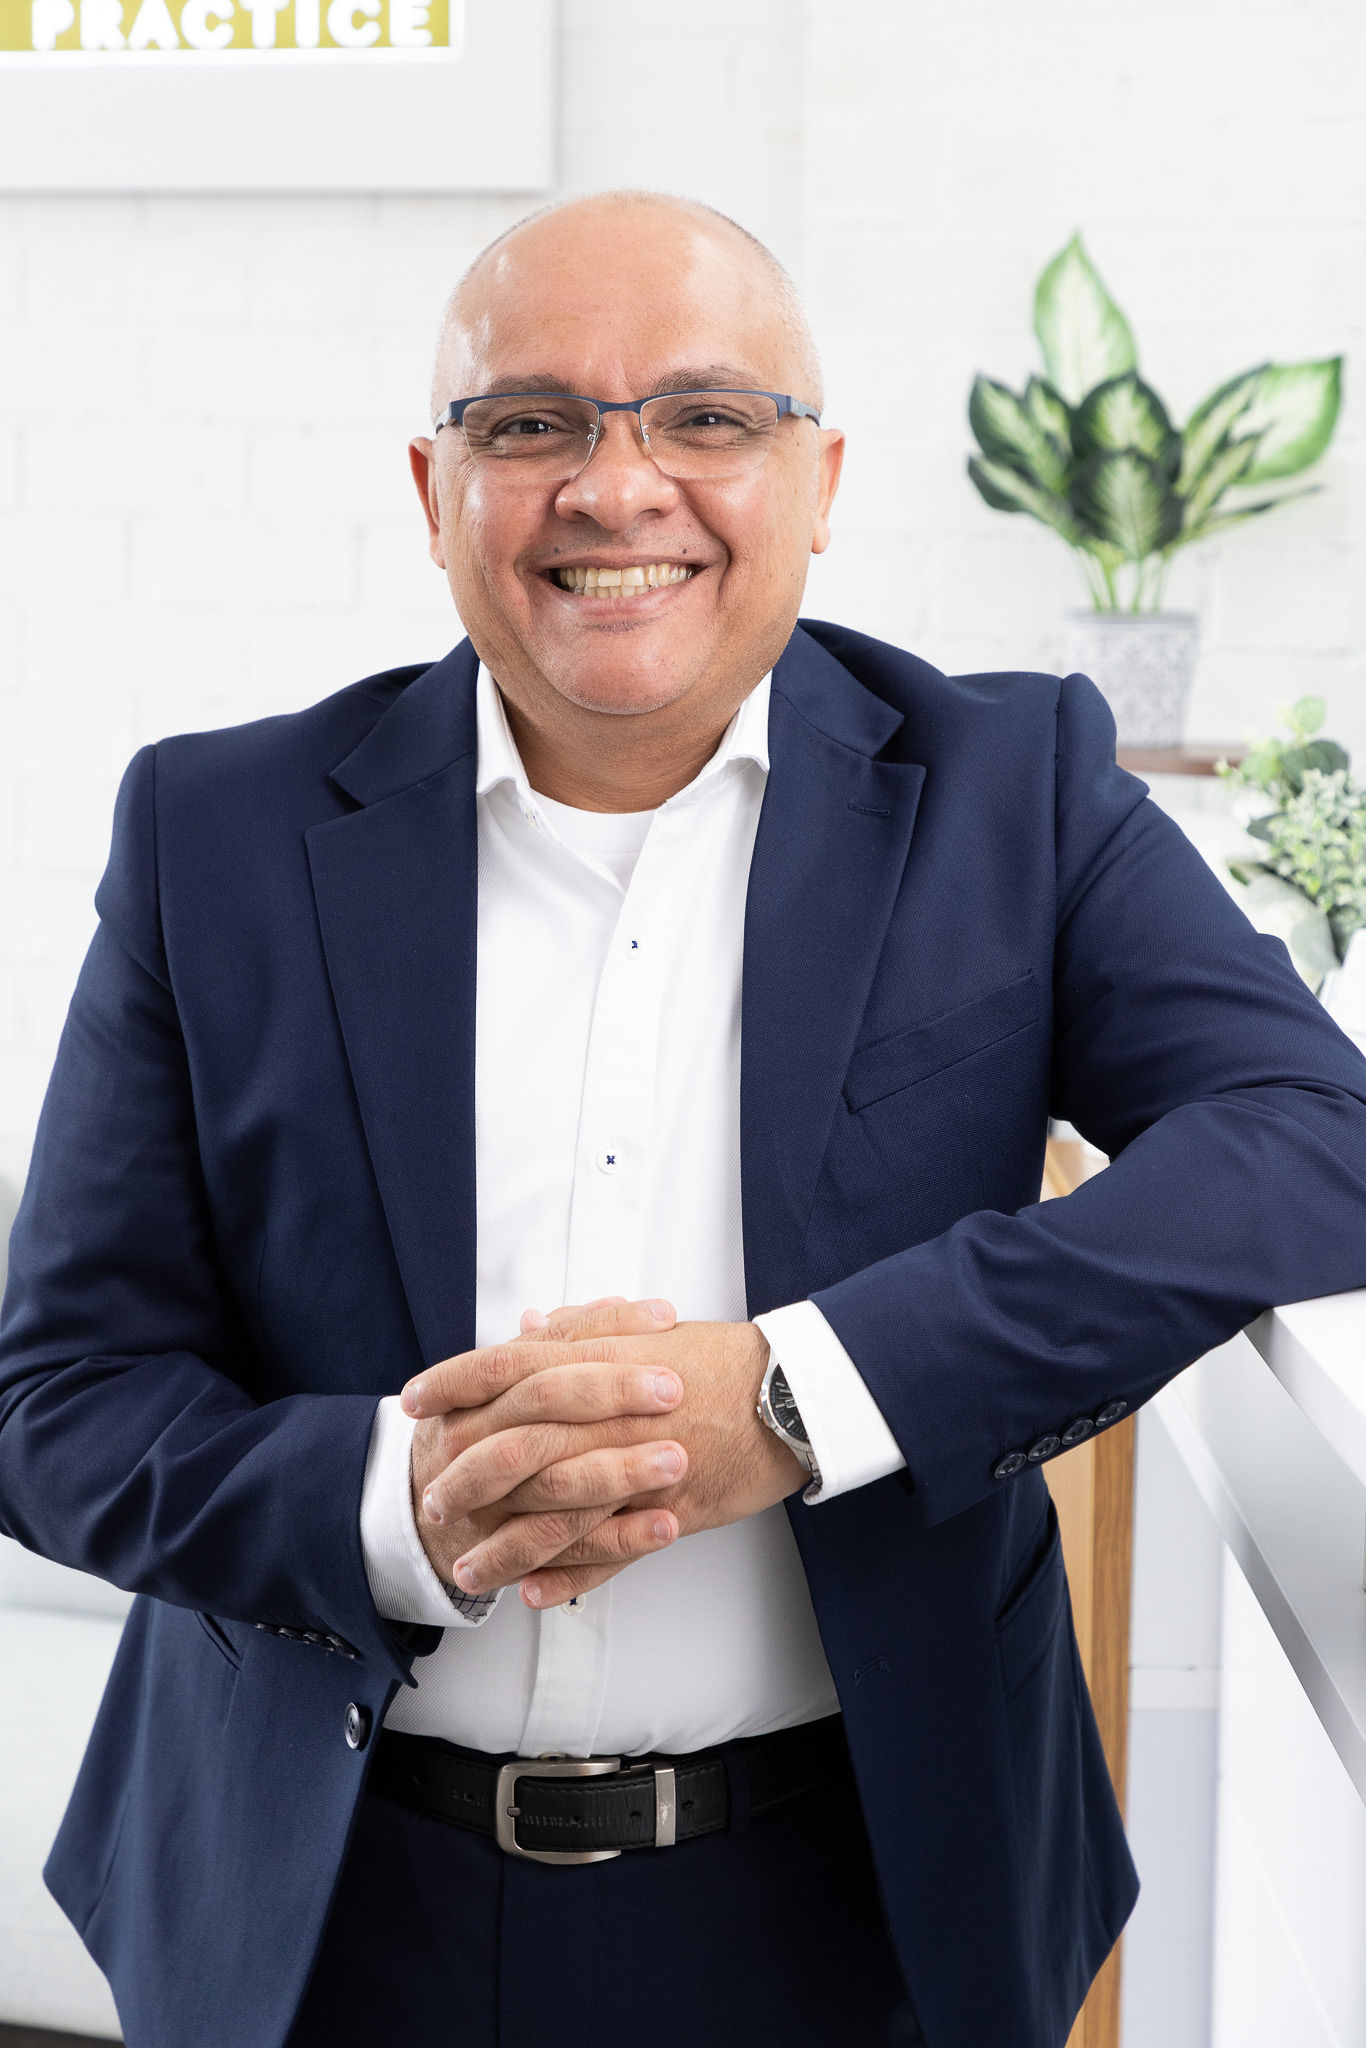
Ramy Hanna
FIPA · FTIA · NTAA · Xero Certified Advisor
Principal & Virtual CFO, VCFO+ Not-for-Profit Australia
Ramy has worked with Australian charities, independent schools, foundations and faith-based organisations since 2003. As Principal of Trinity Accounting Practice and lead Virtual CFO at VCFO+, he helps boards translate financial data into governance decisions they can act on — clearer board packs, stronger reserves, audit-ready books and ACNC-confident compliance.